Market situation · As of October 2026
The recovery is not reaching many mid-sized companies
Order intake in the Swiss tech industry was 12.1 per cent above the previous year in the first half of 2026. However, the growth was carried almost entirely by large companies: SME revenues fell by 3.8 per cent over the same period. At 81.1 per cent, capacity utilisation was well below the long-term average of 85.6 per cent, and around a quarter of companies reported a negative EBIT margin in the previous year.
In Germany, the VDMA expects a real production decline of 2 per cent in machinery and plant engineering for 2026, the fourth in a row. With 38 cases, the number of large insolvencies in German machinery in 2025 was well above the five-year average. In Switzerland, company insolvencies reached their highest level since 1994 in the first half of 2026. Part of the increase is due to public creditors enforcing outstanding claims more consistently since the revision of the Debt Enforcement and Bankruptcy Act.
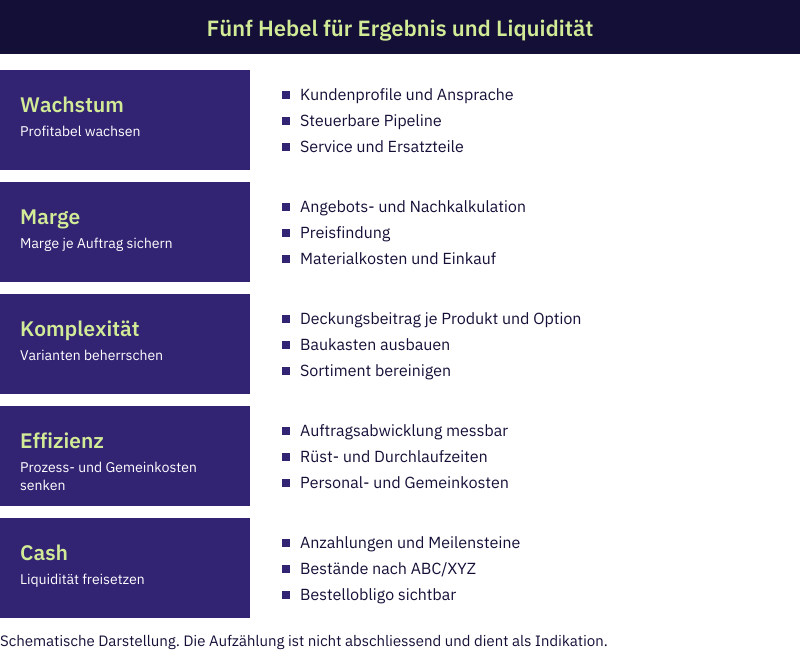
Waiting for demand to return costs time. The companies that put their processes, sales and working capital in order now will emerge stronger from the weak phase.